Bend, Oregon · Licensed independent agency
Health insurance in Bend, where the county line moves the price more than the city limits do.
Deschutes County priced five individual carriers in 2026 and has two for 2027. Drive 36 miles northeast to Prineville and the identical standardized plan from the identical carrier costs about 23% more, because that is a different rating area. Meanwhile one health system runs every hospital in Central Oregon, and the state puts the next closest at about 129 miles. Bend is a market with real quirks, and most of them are invisible on a national comparison site.
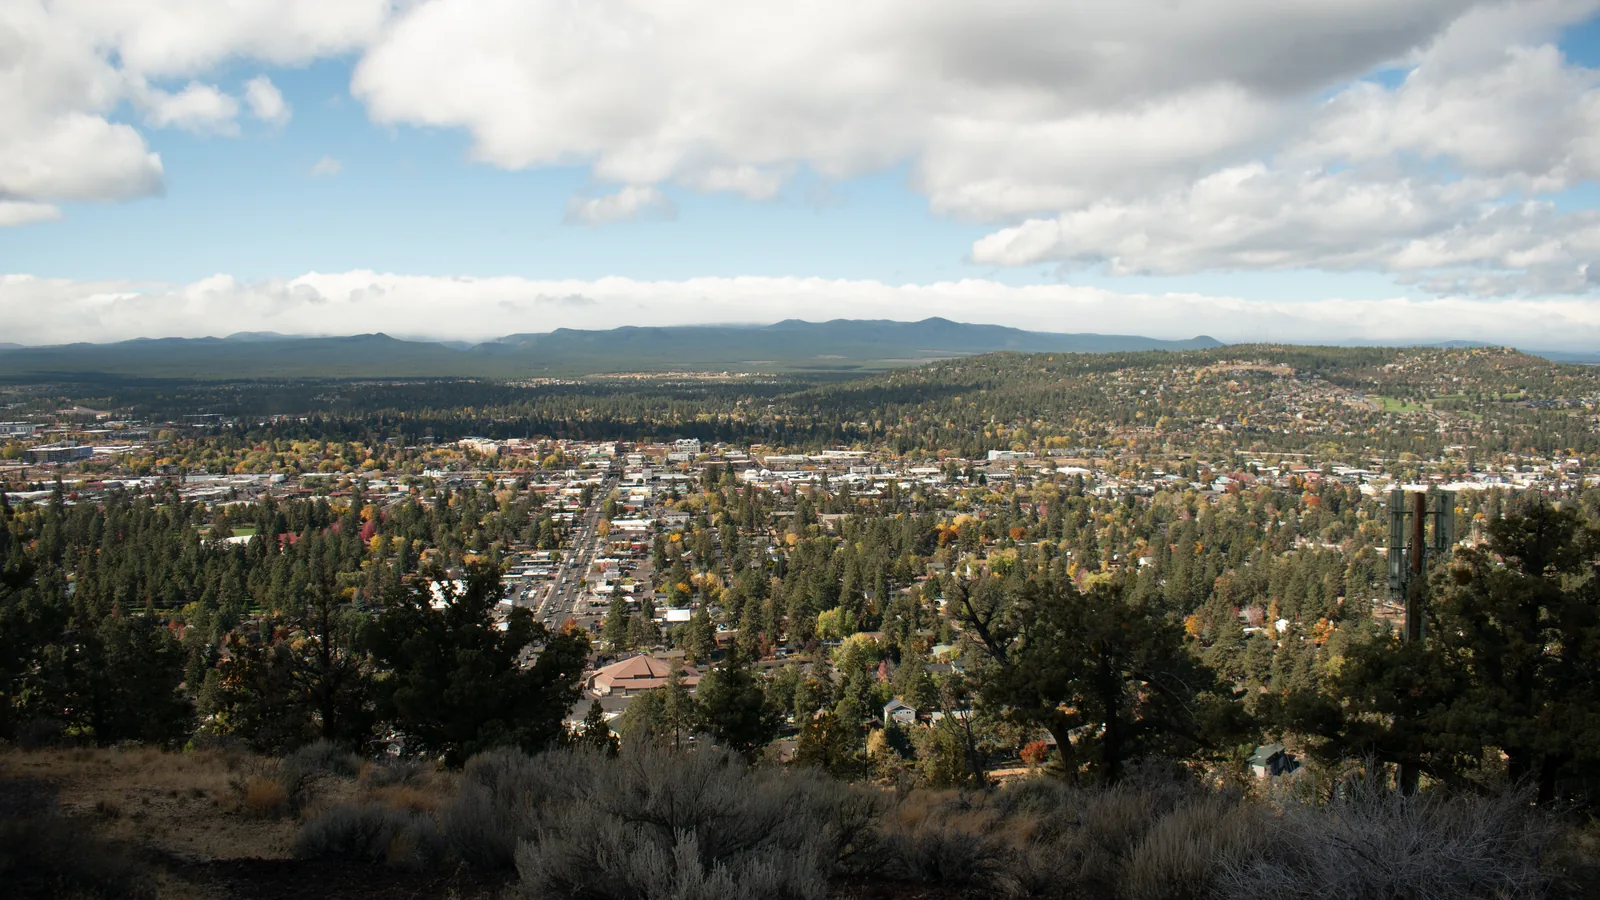
Bend sits in Deschutes County, which is Oregon Rating Area 4 along with Klamath and Lake counties. Crook and Jefferson counties, meaning Prineville and Madras, are in Rating Area 6, so a Central Oregon household can cross a county line and see a materially different price for the same plan. Deschutes also lost three of its five individual carriers for 2027. We check which carriers actually sell at your address, what they cost in your rating area, and whether your doctors are inside the network before you enroll. Apex Health Advisors is an independent, multi-carrier agency licensed across Oregon. Our help costs you nothing, because the commission is built into the premium either way. Call 503-276-7102.
Last updated . We update this page when something in Bend actually changes, not on a schedule.
Deschutes County went from five carriers to two in one year
Three of the five insurers that priced Bend for 2026 are not selling individual plans here in 2027, and most of the county's individual market was with them.
For 2026, five carriers priced individual plans in Deschutes County. For 2027 there are two. Providence Health Plan and PacificSource both left Oregon's individual market entirely, and Moda withdrew from Deschutes and Crook between the state's June proposal and its August final order. What remains in Bend is BridgeSpan and Regence.
The scale matters more here than the headline does. On the state's own enrollment reporting, around half of everyone in Deschutes County who buys their own coverage was with a carrier that will not sell an individual plan in their county next year, and in Crook County it is the large majority. Those households are moving whether they intended to or not.
Deschutes is one of six Oregon counties down to two individual carriers for 2027, alongside Crook, Klamath, Lake, Umatilla and Union. Most of the state has three or four.
Drive to Prineville and the same plan costs about 23% more
Deschutes is Rating Area 4. Crook and Jefferson are Area 6. Same region, same carrier, same standardized plan, different price.
Oregon sets premiums by rating area, and the areas are drawn along whole county lines. Central Oregon is usually spoken of as one region, and the council of governments that serves it covers Crook, Deschutes and Jefferson together. The insurance map does not agree. Deschutes sits in Area 4 with Klamath and Lake. Crook and Jefferson sit in Area 6 with the eastern Oregon counties.
The gap is the area factor, not the plan, which is why it is worth knowing. On the state's published 2026 individual figures, the identical standardized silver plan cost about 23% more in Crook and Jefferson than in Deschutes, Klamath and Lake. The same roughly 23% gap shows up on the bronze and gold standardized plans from that same carrier, to the decimal, because one area factor is doing all of the work. Thirty-six miles of highway, one county line.
Which rating area your Central Oregon county sits in
| Where | Rating area | Relative cost of the same standardized plan |
|---|---|---|
| Bend, Redmond, Sisters, La Pine (Deschutes) | Area 4 | Baseline |
| Klamath Falls (Klamath) | Area 4 | Same as Deschutes |
| Lakeview (Lake) | Area 4 | Same as Deschutes |
| Prineville (Crook) | Area 6 | About 23% more |
| Madras (Jefferson) | Area 6 | About 23% more |
| Portland (Multnomah) | Area 1 | Slightly more than Deschutes |
Scroll the table sideways to see every column.
Source: Oregon Division of Financial Regulation, 2026 plan comparison table, comparing the state's published figures for a 40-year-old before any premium tax credit. Relative, not a quote: approved 2027 rates are higher than 2026, and your own price depends on your age, household, plan and the deductible and out-of-pocket limits that come with it.
Bend is not an expensive place to buy health insurance. This surprises people, because almost everything else in Bend costs more than it used to. On the state's 2026 figures Bend priced the same as Klamath Falls and Lakeview, and slightly below Portland. If someone tells you Central Oregon premiums are high because Bend is an expensive town, that is not what the rate filings show.
One honest qualifier. If you receive a premium tax credit, it is calculated against the second lowest cost silver plan available where you live, which cushions a lot of the area difference. The gap bites hardest on people paying full price, and in a county with the highest per capita personal income of any Oregon county (BEA, 2024) that is a lot of households.
And the choice map is a separate map from the price map, which is where it gets genuinely confusing. Crook is in a different rating area from Deschutes but has the same two carriers for 2027. Jefferson is in the same rating area as Crook but has three. A Madras resident can buy Moda; a Bend or Prineville resident cannot.
- Your county sets your price, not your town or your ZIP. Oregon rates by county with no ZIP splitting, so check which county your address is actually in.
- Some Central Oregon ZIPs straddle the line. Redmond and Terrebonne mailing ZIPs cover land in more than one county, so two neighbors can sit in different rating areas.
- Compare the standardized plans first. Oregon requires carriers to offer them under a fixed naming convention, which makes cross-carrier comparison honest rather than approximate.
One health system owns every hospital in Central Oregon
St Charles runs the hospitals in Bend, Redmond, Prineville and Madras. The nearest hospital it does not run is about 129 miles away.
This is the fact that should shape how you think about networks here, and it comes from the state, not from us. In its 2024 review of a St Charles transaction, the Oregon Health Authority wrote that “St. Charles owns and operates the only hospitals in the Central Oregon region” and that “the next closest hospital is Adventist Health Columbia Gorge Hospital in The Dalles, Oregon, which is approximately 129 miles away.”
St Charles operates four hospitals: Bend, Redmond, Prineville and Madras. St Charles Bend is a Level II trauma center and, per the same state report, the only one east of the Cascades. Prineville and Madras are federally designated Critical Access Hospitals.
What that means practically is the opposite of what people assume. In a city with several competing systems, choosing a network means choosing a hospital. In Bend, if a plan does not work with St Charles, there is no realistic second hospital to fall back on without a long drive. So the network question in Central Oregon is not which system you prefer. It is whether the plan you are considering works with the only one there is.
Primary care is a separate and tighter question. Across the region the supply of physicians is close to the Oregon average, so Deschutes itself is not short. Cross the county line into Crook and it thins dramatically. That is the gap worth planning around, and it is another reason the county line matters more here than the city limits do.
Employer coverage in Central Oregon, where the network question mostly answers itself
One health system runs the hospitals here, so a Central Oregon group decision turns on funding structure and which rating area you sit in.
In Portland an employer's first question is which network includes which hospital. In Central Oregon that question largely answers itself, because the same health system runs the hospitals in Bend, Redmond, Prineville and Madras. Carriers are contracting with the same facilities, so the network is rarely what separates one Central Oregon group quote from another.
What does separate them is the rating area in the table above, and how the plan is funded. Oregon leaves the door open to level-funded designs for small employers, where a compliant stop-loss contract sits alongside a self-funded medical plan instead of a fully insured small group policy. That matters here, because a Deschutes employer and a Crook employer with identical employees do not start from the same fully insured baseline.
Renewals are also not a January event in Oregon. The state permits small group rates to be filed quarterly, so anniversaries land across the year. If your renewal is in April or July, that is an ordinary Oregon renewal and not a reason to wait for winter.
What we cannot tell you yet, and why we will not pretend otherwise
The two carriers left in Bend for 2027 are the two whose network files we could not independently verify. We will check yours directly rather than guess.
Carriers publish machine-readable network files, and for the 2026 plan year we could confirm directly that St Charles Bend was in network on PacificSource, Moda and Providence individual plans. Those are the three carriers leaving. For the two that remain, BridgeSpan and Regence, the published network files sit behind bot protection and we could not read them independently.
We are telling you that rather than papering over it, because the alternative is a confident claim we cannot support. What we will do is check the specific 2027 plan you are considering against St Charles and against your own doctors, directly with the carrier, before you enroll.
There is a related trap worth knowing, and we saw it in the 2026 data. In-network status can differ between products from the same insurer. For 2026, St Charles appeared on two of one carrier's individual networks and was absent from a third from that same carrier. “My insurance company covers St Charles” is not a safe inference. The plan covers it, or it does not.
Who this actually lands on in Deschutes County
A county full of one-person businesses and people in their late fifties, which is exactly the population that buys its own coverage.
Deschutes County runs on one-person businesses and small employers to an unusual degree, with a far higher concentration of sole proprietors than Oregon as a whole, most employer businesses under ten people, and a work-from-home share well above the state's. That is a lot of households with no HR department and no group plan to fall back on.
The age profile compounds it. Deschutes skews older than the state, with a large band of residents in their late fifties and early sixties. That band is the most expensive to cover and the least able to wait it out, because Medicare is still years away.
We are not going to tell you Bend has a coverage crisis, because it does not. The county's uninsured rate is better than Oregon's. This is not a place where people cannot get covered. It is a place where a lot of people buy their own coverage, in a market that just lost most of its options, in the second year since the enhanced federal premium tax credits expired at the end of 2025. Premium tax credits still exist for households between 100 and 400% of the federal poverty level, but the enhanced amounts and the removal of the 400% cap are gone, so the hard cliff at 400% is back. Those are different problems and they need different advice.
If your income sits between roughly 138 and 200% of the federal poverty level, check OHP Bridge before you shop.
What working with us looks like in Bend
Licensed across Oregon, paid by the carrier, and straight about what we do not know.
We are an independent agency licensed across Oregon, and our help costs you nothing because the carrier pays us. Rates are filed with and approved by the state, so going through an agent does not change your price. State approval of a rate does not constitute a recommendation or endorsement of any company or policy. What changes is that somebody checks your county, your carriers, your hospital and your prescriptions before you commit.
We have no Central Oregon office. We are licensed across Oregon and write coverage in all 36 counties. What you get instead is somebody who already knew Deschutes and Crook are in different rating areas before you called.
We can only place carriers we are appointed with, and if the better plan for you is one we do not carry, we will say so. We also serve Redmond and Terrebonne, Sisters, La Pine, Sunriver and the rest of the county, and the county line question matters more for some of those addresses than others. More on the state as a whole on our Oregon page.
Common questions
Bend questions, straight answers
Why does my cousin in Prineville pay more than I do in Bend for the same plan?
Because Oregon prices by rating area and the two of you are in different ones. Deschutes County is in Rating Area 4, along with Klamath and Lake counties. Crook County, where Prineville is, is in Rating Area 6 with the eastern Oregon counties, as is Jefferson County and Madras. On the state's published 2026 figures the identical standardized silver plan ran about 23% more in Crook and Jefferson than in Deschutes, and the same gap appears on the bronze and gold standardized plans, because it is the area factor rather than the plan. The areas are drawn by whole county with no ZIP code splitting, so it is your county that decides, not your town. Approved 2027 rates are higher than the 2026 figures across the board.
Is Bend an expensive place to buy health insurance?
No, and this one surprises people. On the state's 2026 figures Bend priced the same as Klamath Falls and Lakeview, and slightly below Portland, for the same standardized plan. Almost everything else in Bend has gotten more expensive, so the assumption is understandable, but the rate filings do not support it. What Bend has is fewer choices, not higher prices.
My plan is going away. How many options do I actually have in Bend for 2027?
Fewer than you had. Five carriers priced individual plans in Deschutes County for 2026 and two do for 2027, which puts Deschutes among the six Oregon counties with the fewest choices, alongside Crook, Klamath, Lake, Umatilla and Union. Providence and PacificSource left Oregon's individual market entirely and Moda withdrew from Deschutes and Crook between the state's proposed and final 2027 orders. That is exactly why we start with which doctors and which hospital you need rather than with the premium.
Will my plan cover St Charles?
That is the right question to ask in Central Oregon, and we will verify it for the specific plan rather than guess. St Charles operates every hospital in the region, in Bend, Redmond, Prineville and Madras, and the Oregon Health Authority has stated the nearest hospital it does not run is about 129 miles away in The Dalles. So a plan that does not work with St Charles has no realistic local alternative. One caution from the 2026 network data: in-network status can differ between products from the same insurer, so a carrier-level answer is not good enough. We check at plan level, directly.
I am self-employed in Bend. Does that change anything?
More realistic than most owners assume. Deschutes County has an unusually high concentration of sole proprietors and very small employers, so a large share of local households buy their own coverage with no group plan behind them. If you have at least one employee on payroll who is not an owner or an owner's spouse, it is worth pricing, and Oregon small group is guaranteed issue year round so you are not waiting for a window.
Does it cost anything to work with you?
No. There is no fee and no markup, and rates are filed with and approved by the state, so your price is the same whether you enroll through an agent or on your own. State approval of a rate does not constitute a recommendation or endorsement of any company or policy. What changes is that someone checks your county, the carriers that actually sell at your address, and whether your doctors and prescriptions are inside the network. If the honest answer is that you belong on OHP Bridge or the Oregon Health Plan instead, we will tell you, and we make nothing when we do.
Apex Health Advisors LLC is not affiliated with or endorsed by the U.S. government or the federal Medicare program.
We do not offer every plan available in your area. Currently we represent 3 to 4 organizations which offer 7 to 32 products in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options. TTY users can call 1-877-486-2048. The line is open 24 hours a day, 7 days a week.
Plan availability is set county by county, so the exact counts depend on where you live. Tell us your county and we will confirm the numbers for your address.
Ready to see your options?
Tell us a little about your situation and a licensed insurance agent gets back to you, usually the same business day and often within minutes during business hours. No spam, no obligation.
This is a solicitation of insurance. A licensed agent may contact you.